Estate planning increasingly requires advisers to understand more than the assets held within an advised portfolio. A client’s wider financial position may include property, pensions, savings, business interests, protection policies, liabilities, trusts, and other assets held across different providers or ownership structures.
The planning context can also extend beyond the individual client. Spouses, children, dependants, beneficiaries, executors, attorneys, solicitors, accountants, and other professionals may all have a role in how wealth is managed, transferred, or administered over time.
For advisers, the challenge is building enough context to understand how a client’s assets, liabilities, family relationships, ownership structures, estate documents, and future wishes connect.
What is estate planning software?
Estate planning software is a broad term covering technologies that help advisers gather, organise, analyse, or maintain information relevant to a client’s estate and future wealth transfer.
Different systems support different parts of the process, including:
- Customer relationship management (CRM) systems for maintaining the firm’s client record
- Cashflow-planning software for modelling future financial scenarios
- Open Finance for improving visibility of connected financial accounts
- Specialist estate-planning tools for technical analysis and modelling
- Document platforms for storing and sharing important records
- Client-controlled records for maintaining a broader view of the client’s circumstances
For advice firms, the key consideration is how these technologies work together to create a more complete view of the client, rather than expecting one system to manage the entire estate-planning process.
How different technologies support estate planning
CRM systems
CRMs remain central to the management of the adviser-client relationship. They typically hold contact information, fact-find data, meeting notes, correspondence, review dates, advice records, and other information required for servicing and compliance.
They can also record spouses and partners, children and dependants, beneficiaries, executors, attorneys, and other important contacts. However, this information is generally maintained through the firm’s own interactions with the client.
Family circumstances, ownership arrangements, beneficiary details, liabilities, and held-away assets can change between reviews and may not be reflected in the CRM until the client tells the firm. The CRM remains an important professional record, but it may not always reflect the client’s wider circumstances in real time.
Cashflow-planning software
Cashflow-planning software helps advisers assess how current financial arrangements and future decisions may affect a client over time. Within estate planning, advisers can use these tools to model retirement income, expenditure, lifetime gifting, care costs, inheritance scenarios, and the affordability of different wealth-transfer strategies.
The model is only as useful as the information behind it. If held-away assets, liabilities, family commitments, or future needs are not included, the projection may not reflect the client’s full financial position.
Open Finance
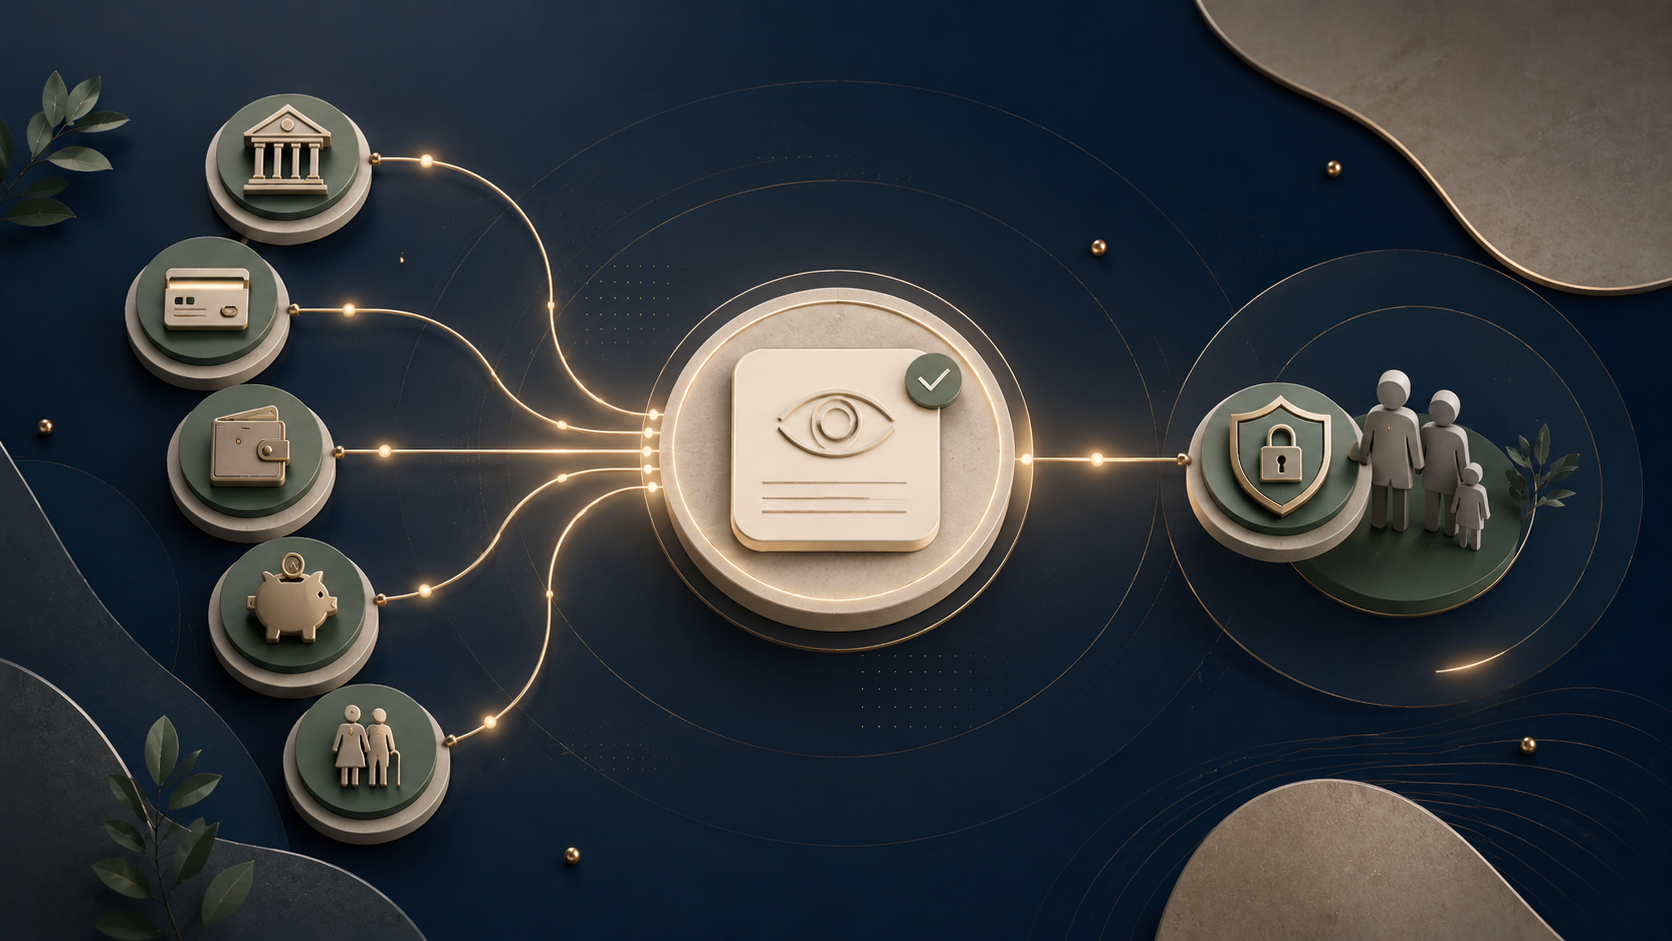
Open Finance can improve visibility by allowing clients to connect bank accounts, investments, pensions, mortgages, and other financial products. Connected data can reduce reliance on manually entered balances and give advisers a broader view of assets and liabilities outside the advised portfolio.
Account data still provides only part of the estate-planning picture. A connected account may show the existence and value of an asset without explaining its ownership, intended beneficiary, family context, or related estate documents. Those details need to be considered alongside the financial data when building a wider view of the client’s estate.
Specialist estate-planning tools
Specialist estate-planning software can support more technical areas of the planning process, including:
- Inheritance tax calculations
- Gifting strategies
- Trust planning
- Estate projections
- Family mapping
- Beneficiary information
- Ownership structures
These systems can help advisers analyse potential outcomes and structure discussions around wealth transfer, but the quality of that analysis depends on the completeness and accuracy of the underlying information.
Assets, liabilities, relationships, or documents that have not been identified will not be reflected in the analysis. Specialist tools can strengthen technical planning, but they sit alongside professional judgement and, where needed, legal, tax, or accounting advice.
Document platforms
Document platforms and client portals provide secure environments for storing and exchanging records such as wills, Lasting Powers of Attorney (LPAs), trust documents, insurance policies, valuations, tax records, and ownership documents.
A centralised document platform can make important records easier to locate and share. However, storage alone does not establish whether the information remains current. A document may be stored securely even though the client’s circumstances have changed since it was prepared. For example, a will may still name beneficiaries or executors who no longer reflect the client’s current wishes or family circumstances. These systems work best alongside structured, up-to-date information about the client’s wider circumstances.
Client-controlled records
Client-controlled records take a different approach to information management. The client maintains a wider record for their own use and decides which information to share with trusted individuals and professionals.
This may include financial accounts, property, liabilities, family relationships, beneficiaries, executors, attorneys, estate documents, and wishes. Advisers can access relevant information without requiring the CRM to become the sole record of the client’s wider circumstances. As the client updates the record over time, advisers may gain access to more current information between annual reviews, subject to the permissions the client has granted.
Why the advised portfolio is not enough
An adviser may have detailed information about the investments, pensions, or products managed by their firm while still having limited visibility of the client’s wider estate.
Important information may sit elsewhere, including:
- Held-away savings and investments
- Property and business interests
- Protection policies
- Trusts
- Liabilities
- Assets managed by other providers
- Different forms of ownership
The advised portfolio also does not show the full family context around those assets, including spouses, children, dependants, and future beneficiaries who may be affected by future planning decisions. Taken together, this wider information gives advisers a more complete view of the client’s estate.
Firm-held client data and client-controlled information
Most financial advice firms already hold client data, including regulated advice records, fact finds, correspondence, identification, financial information, and meeting notes. This firm-held information supports advice delivery, compliance, relationship management, and the record of professional decisions.
Client-controlled information serves a different purpose. It is maintained primarily for the client and can include a broader range of personal, financial, family, and estate information than the firm would ordinarily need to collect.
The client can update that record as circumstances change and choose which parts to share with financial advisers, family members, solicitors, accountants, or other trusted professionals. The adviser can then access the information the client has chosen to share without taking responsibility for maintaining the client’s entire wider record.
The two records serve different purposes and work alongside one another. The CRM remains the firm’s professional system of record, while client-controlled information adds context around the client’s wider circumstances.
Supporting collaboration between professionals
Estate planning often involves several professional relationships. Financial advisers may focus on financial strategy, while solicitors advise on wills, trusts, LPAs, and estate administration. Accountants or tax specialists may contribute where business interests, tax planning, or complex ownership structures are involved.
With the client’s permission, relevant information can be shared across the professional team, helping advisers, solicitors, accountants, and tax specialists work from a more consistent view of the client’s circumstances. Relevant information may include assets and liabilities, family relationships, ownership arrangements, beneficiary details, estate documents, and recent changes.
Permissioned access can support collaboration without giving every professional access to the client’s entire record. The client decides what to share, while each professional remains responsible for checking the information relevant to their work and advising within their own area of expertise.
What advisers should consider when choosing estate planning software
More technology does not automatically improve the estate-planning process. Firms need to consider how any new system fits alongside their existing CRM, cashflow-planning software, platforms, document systems, and adviser workflows.
Key considerations include:
- Integration: Technology should work effectively alongside existing systems without creating additional information silos or duplicate data entry.
- Data accuracy and updates: Firms should understand where information comes from, who maintains it, and how recently it has been updated as circumstances change.
- Client adoption: Client-facing tools are more valuable when clients have a practical reason to continue using and updating them.
- Security and permissions: Sensitive information requires appropriate protection and access controls, with clients able to decide what different people and professionals can view.
- Professional responsibility: Technology can help organise information and support analysis, but it does not replace the adviser’s judgement. Relevant information should still be checked before it forms the basis of advice.
Useful technology should make relevant information easier to access and use without adding unnecessary complexity to the advice process. Firms should assess each technology by how it contributes to the wider advice process, rather than considering individual features in isolation.
Where Lyfeguard fits
Lyfeguard works as a client-intelligence layer alongside the adviser’s CRM, planning tools, and professional judgement. Clients can bring together financial information, assets, liabilities, property, family relationships, beneficiaries, executors, attorneys, documents, wishes, and other information in one secure record.
Clients choose which information to share with their adviser, family members, solicitors, accountants, or other trusted individuals. Permissioned access gives advice firms additional context around held-away assets, ownership, family structures, estate information, and changes in circumstances.
Lyfeguard does not replace the CRM, cashflow-planning software, specialist estate-planning tools, or adviser expertise. Instead, it provides an additional information layer for understanding the client, their assets, relationships, and responsibilities.