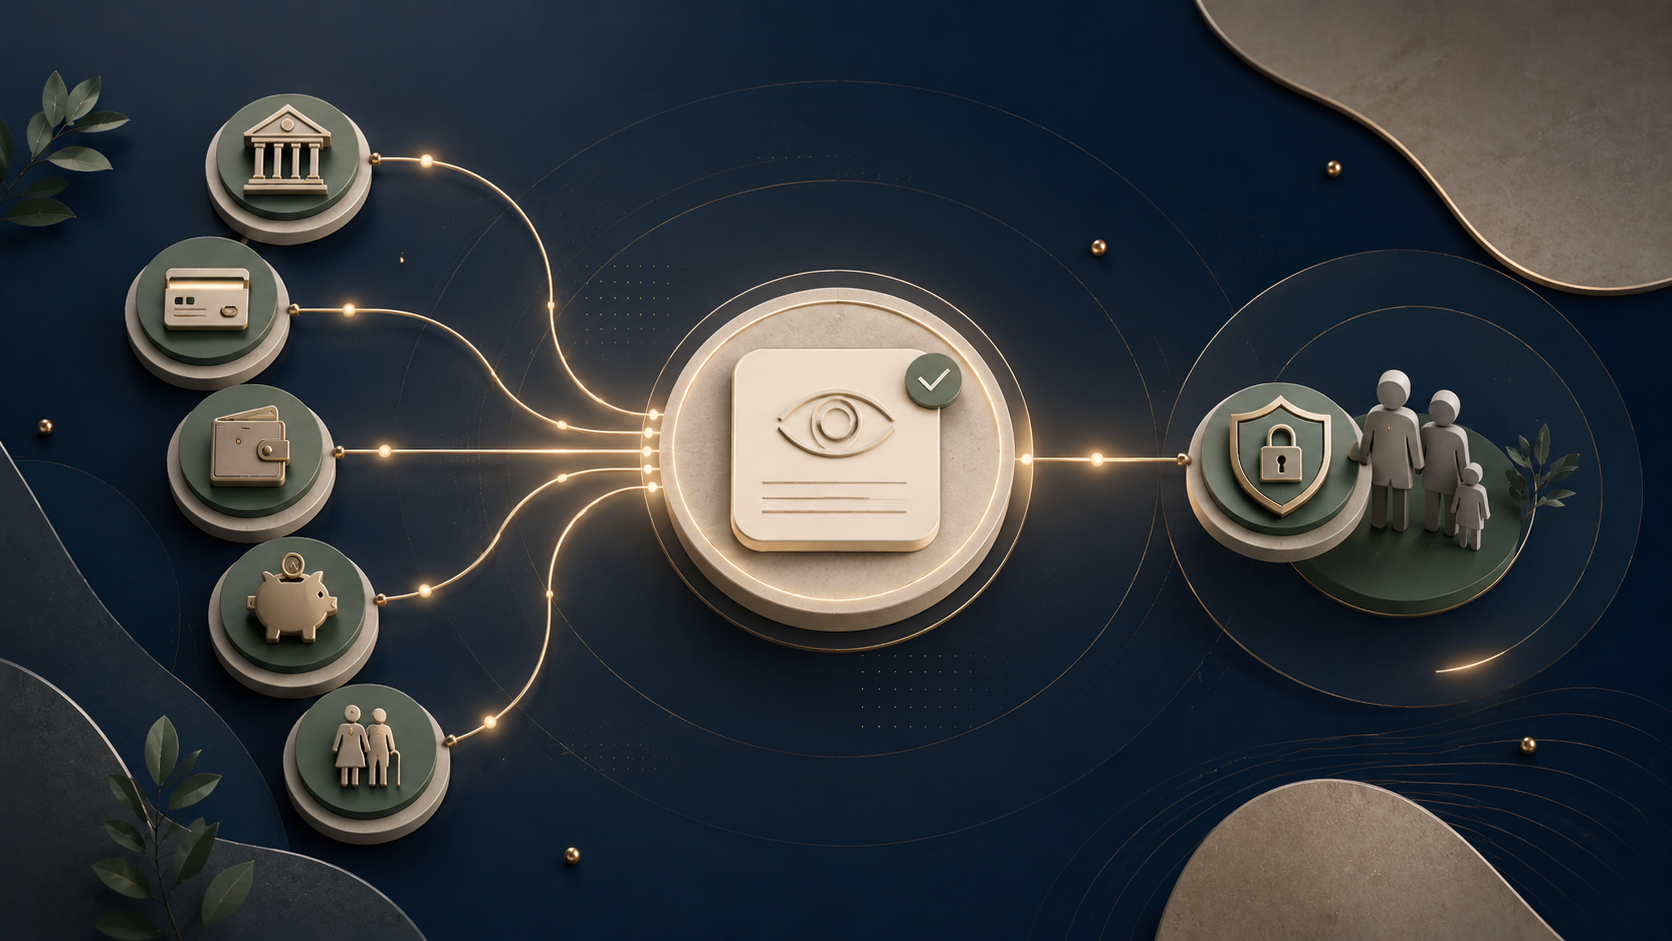
A client’s advised portfolio rarely represents their entire financial position. Cash may sit across several banks, pensions can remain with previous employers, investments may be held on other platforms, and property or business interests can sit outside the adviser relationship.
Clients may overlook these assets because their finances are fragmented, they are unsure of current values, or they do not believe the information is relevant to the advice they are receiving.
A more complete view can help advisers understand liquidity, financial resilience, existing commitments, and how different assets fit around the client’s objectives. The purpose is not simply to identify assets that could be brought under advice, but to understand the client’s wider financial position and determine whether anything requires further discussion.
What are held-away assets?
Held-away assets are financial or other assets that form part of the client’s wider financial position but are not currently managed or advised on by the firm.
They can include:
- Cash and savings held with other banks or building societies
- Pensions from current or previous employers
- Investments held on other platforms or directly with providers
- Property
- Business or partnership interests
- Insurance policies with a financial value or relevant protection benefit
- Workplace benefits and share schemes
- Jointly held accounts or assets
- Other investments or financial arrangements outside the advised relationship
The relevance of each asset will depend on the client and the advice being provided. A small savings account may have little impact on one recommendation, while a large cash balance, old pension, jointly owned property, or business interest may materially affect another.
Why held-away assets can be difficult to identify
Clients do not always have a single, organised view of their finances. Accounts may have accumulated over many years, pensions can remain with former employers, investments may sit across several providers, and important documents can be spread across paper files, emails, portals, and online accounts.
Uncertainty can also affect what clients disclose. A client may know that an investment exists without knowing its current value or remember an old workplace pension without having recent documentation.
Some clients may not realise that assets outside the adviser relationship are still relevant. A bank account, property, insurance policy, or jointly held investment may be left out because the adviser is not currently responsible for it.
Advisers need a process that helps clients identify what exists without implying that every asset should become part of the advised portfolio.
Using fact-finds to identify held-away assets
Fact-finds provide a structured way to ask clients about their financial circumstances during onboarding, reviews, and other advice interactions.
Questions about cash, investments, pensions, property, liabilities, income, and existing financial products can prompt clients to consider assets that might otherwise be missed. A well-designed fact-find can also create consistency across the firm by ensuring advisers cover the same broad areas with different clients.
The main limitation is that a fact-find reflects the information available at a particular point in time. Clients may enter approximate values, leave fields incomplete, or forget assets altogether. Information can also become outdated as accounts close, balances change, property is bought or sold, and new workplace arrangements are created.
Fact-finds are useful for establishing a starting point, but they should not be treated as a permanently complete record of the client’s financial position.
Open Finance and connected financial information
Open Finance can help advisers access financial information held across supported providers with the client’s permission.
Connections can reduce manual data entry and provide a more current view of supported accounts, investments, pensions, credit, and other financial products. They can also make it easier to identify assets held outside the existing advice relationship when those providers and account types are available through the connection.
Open Finance does not cover every type of asset or provider. Property, private businesses, some pensions, insurance arrangements, workplace benefits, physical assets, and investments held with unsupported providers may sit outside an Open Finance connection.
Connections can also expire or require renewed permission, and the information available will depend on the provider and service involved.
Open Finance can provide useful visibility, but it should be treated as one source of information rather than a complete view of the client’s held-away assets.
Provider statements and uploaded documents
Provider statements can help advisers verify information supplied by the client and provide more detail about an account, pension, investment, or policy.
Clients may also upload statements, policy documents, pension information, property records, or other relevant documentation as part of the advice process.
Documents can be particularly useful where an asset cannot be connected digitally or where additional detail is needed. They may help clarify ownership, provider information, values, and product characteristics.
The main limitation is how current the information is. A statement may reflect a balance or valuation from several months earlier, while the underlying asset may have changed since the document was produced.
Document collection can also become fragmented if files are spread across email, portals, document-management systems, and personal records. Advisers may know that a document exists without having a current view of the asset it represents.
Client-maintained records
A client-maintained record can help capture held-away assets that sit outside connected systems or formal advice processes.
Clients can record information about property, cash, business interests, insurance, pensions, jointly held assets, and other arrangements even where live data connections are unavailable.
The main benefit is continuity. Clients can keep relevant information up to date over time rather than rebuilding the full picture during each review.
Manually maintained information still needs appropriate judgement. Values may be approximate, dates may be unclear, and some information may need verification before it can be relied upon for regulated advice.
Firms should also be able to distinguish between live connected data, provider documentation, client-entered information, and information that has been professionally verified.
Giving held-away cash particular attention
Held-away cash can appear straightforward, but the reason a client is holding it may be as important as the balance itself.
A large cash position may be intended for a property purchase, tax payment, business investment, family support, or other planned expenditure. It may also reflect a preference for liquidity or a desire to maintain greater financial resilience during uncertain circumstances.
Some clients may be unsure how much cash they need to retain, while others may have accumulated balances across several accounts without making a deliberate decision about the overall amount.
A clearer understanding of the purpose of the cash can help advisers distinguish between funds that need to remain accessible and money that may warrant further discussion as part of longer-term planning.
The conversation should consider liquidity needs, planned expenditure, uncertainty, emergency reserves, and the client’s wider financial resilience rather than treating a cash balance simply as an investment opportunity.
Consent and permission
Greater visibility of held-away assets should remain dependent on appropriate client permission.
A client may agree to connect a financial account, provide a provider statement, upload a document, or share information from a client-controlled record. Each method gives the adviser access to different information and may involve different permissions.
Permission to view information should not be confused with authority to transact on an account, transfer an asset, or make decisions on the client’s behalf.
Clients should understand what information is being requested, why it may be relevant, and how it will be used. Access should remain proportionate to the advice relationship and the client’s needs.
Keeping information current
Held-away asset information can become outdated quickly as balances change, accounts close, investments move between providers, property is bought or sold, and workplace benefits change.
Firms need to understand when information was last updated and where it came from. Live connections may provide more current information for supported assets, while provider statements reflect a particular date and client-maintained records may rely on manual updates.
Manually entered information may need confirmation where it influences advice. A useful client record should make the source and freshness of information clear rather than presenting every data point as equally current or authoritative.
Framing the conversation around understanding
Clients may be more comfortable sharing held-away asset information when advisers clearly explain why it is being requested.
A conversation focused too heavily on asset gathering may create the impression that the firm is mainly interested in bringing more money under management.
A clearer explanation can help clients understand why the information matters. Advisers may need a broader view of the client’s finances to assess liquidity, existing commitments, diversification, resilience, tax considerations, family circumstances, or progress towards financial objectives.
Disclosure should not automatically lead to a recommendation to transfer or consolidate an asset. Any next step should depend on the client’s needs and the adviser’s professional assessment.
What happens after a held-away asset is identified?
The discovery of a held-away asset does not always lead to a change in advice or action. The appropriate next step will depend on the asset, the client’s circumstances, and the scope of the advice.
Possible outcomes include:
- Further review: The asset may need closer consideration if it could affect existing advice or reveal information that was not previously available. Additional documentation or further analysis may be required before any decision is made.
- Referral: Property, tax, legal, business, or other specialist matters may need input from another professional where they fall outside the adviser’s expertise.
- Consolidation: Assets may be brought together where this supports the client’s objectives and the relevant advice requirements are met.
- No action: The asset may already serve its intended purpose, sit outside the scope of the advice, or have no reason to move.
The value lies in understanding that the asset exists and considering its relevance, rather than assuming that discovery should lead to additional business.
Where Lyfeguard fits
Lyfeguard provides client-intelligence and personal-information infrastructure that can sit alongside a firm’s CRM, planning, portal, and advice systems.
Clients can organise information about cash, investments, pensions, property, liabilities, business interests, insurance, workplace benefits, and other areas of their financial lives within a client-controlled record.
Permissioned sharing can give advisers visibility of relevant held-away information, including assets that may not be available through Open Finance or the firm’s existing systems. Clients can also update information as circumstances change.
Lyfeguard does not control, manage, or take custody of client assets. It also does not replace provider records, fact-finds, Open Finance connections, regulated advice, or professional verification. Lyfeguard provides an additional source of client-maintained information that advisers can consider alongside their existing advice processes.